FREE & FLEXIBLE Retirement
Even if you don’t contribute, M.C. Dean contributes 2% of eligible wages to your 401(k). Grow your retirement savings faster with one of the strongest company contributions available.
Even if you don’t contribute, M.C. Dean contributes 2% of eligible wages to your 401(k). Grow your retirement savings faster with one of the strongest company contributions available.
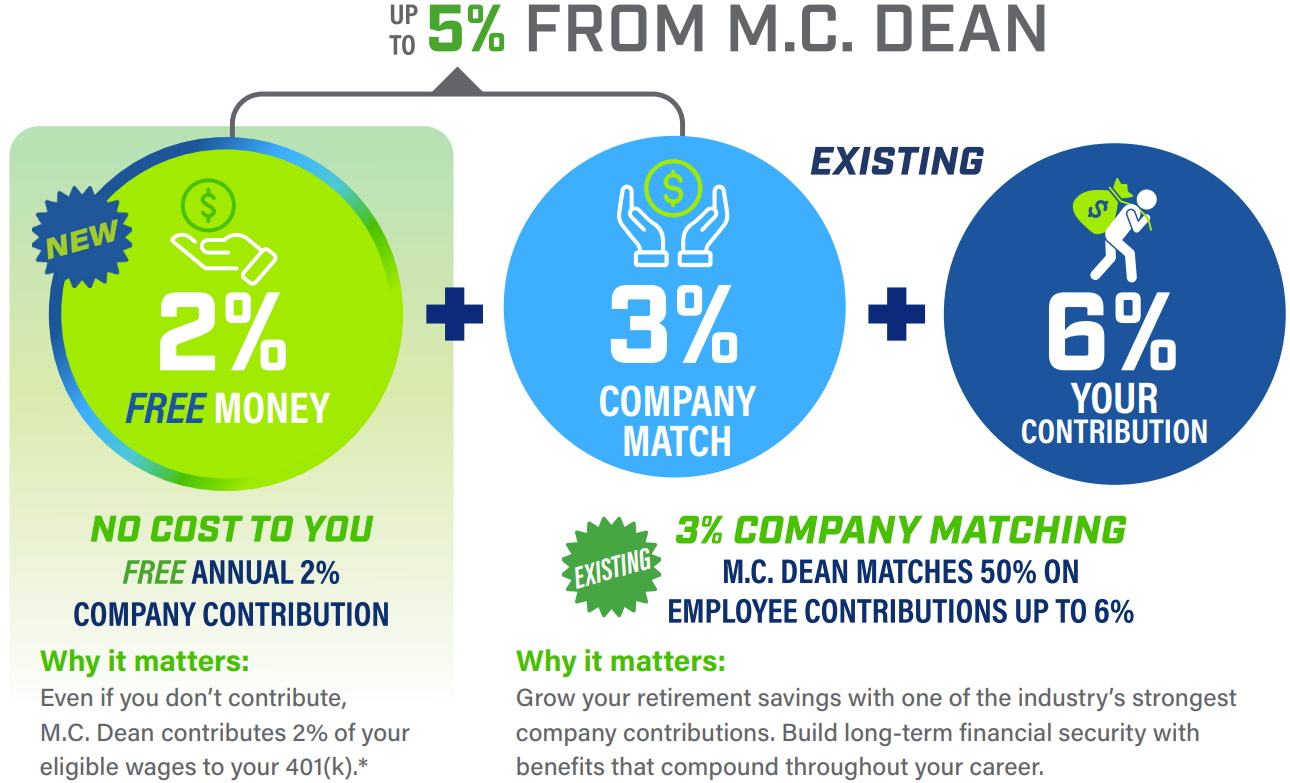
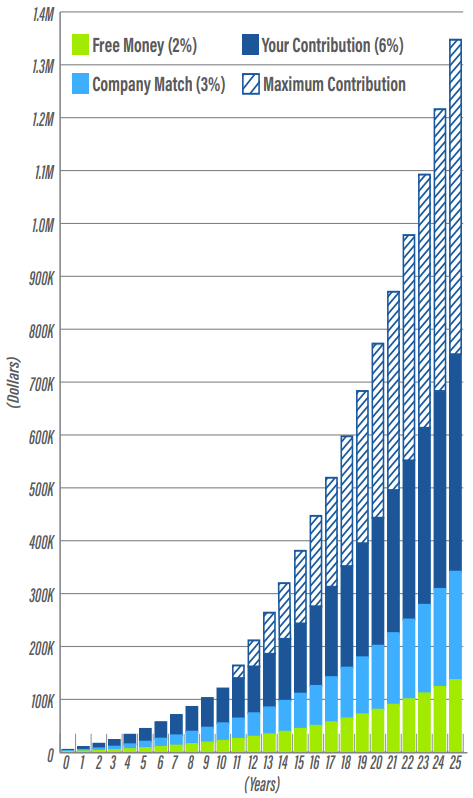
An employee starting at $20/hour ($41,600 annual salary) contributes 6% ($2,496) to receive M.C. Dean’s full 3% match ($1,248), plus the automatic FREE 2% from M.C. Dean ($832). As promotions increase pay, their contributions grow. Starting in year 11, they begin maxing out their 401(k). These investments grow to over $1 million over 25 years (see chart).
*Available after 1 year of service and fully vested after 3 years. Eligible wages exclude overtime, supplemental pay, and bonuses. Payment made in Jan. for prior calendar year. First payment in Jan. 2028.
Explore the flexibility of M.C. Dean’s 401(k) and the resources available to help you plan for retirement.
Health Advocate’s EAP offers confidential, no-cost support to help employees and their families manage financial, legal, personal, and emotional challenges. Take advantage of financial wellness resources:
An employer-sponsored retirement savings plan that allows you to make contributions through salary deferrals (typically a percentage of pay that you choose to have automatically deducted from each paycheck). You can have a traditional 401(k), a Roth 401(k), or both. M.C. Dean offers both Traditional 401(k)s and Roth 401(k)s, both eligible for the company match.
A retirement savings option available to anyone with earned income. You open it yourself and fund it with your after-tax dollars. You can have a traditional IRA or a Roth IRA or both. IRAs have significantly lower annual contribution limit than 401(k)s as well as income limits, and they have different withdrawal rules than 401(k)s.
This money is not taxed when it is put into your account. Pre-tax contributions and any earnings continue to grow tax-free until you start making withdrawals. Pre-tax contributions are eligible for the company match.
Roth contributions are made with after-tax dollars. You pay income taxes now on Roth contributions, but qualified withdrawals of your contributions and earnings are tax-free, provided you are at least age 59½ and meet the five-year participation requirement. Roth contributions are eligible for the company match.
These are made with after-tax dollars and are not eligible for an employer match. By comparison, eligible pre-tax and Roth 401(k) contributions are eligible for the company match.
You will not owe taxes on a withdrawal of your traditional after-tax contributions; however, unlike Roth contributions, you will owe income taxes on the earnings at the time of withdrawal.
Our M.C. Dean 401(k) plan also allows you to use a “backdoor” strategy to convert traditional after-tax contributions to Roth money immediately. When converted, you won’t pay income taxes on future earnings either.
The process of allowing employees to own any contributions made by their employer to their retirement account. This is typically time-based.
Review your options, see what’s new, and make the best choice for you and your family.